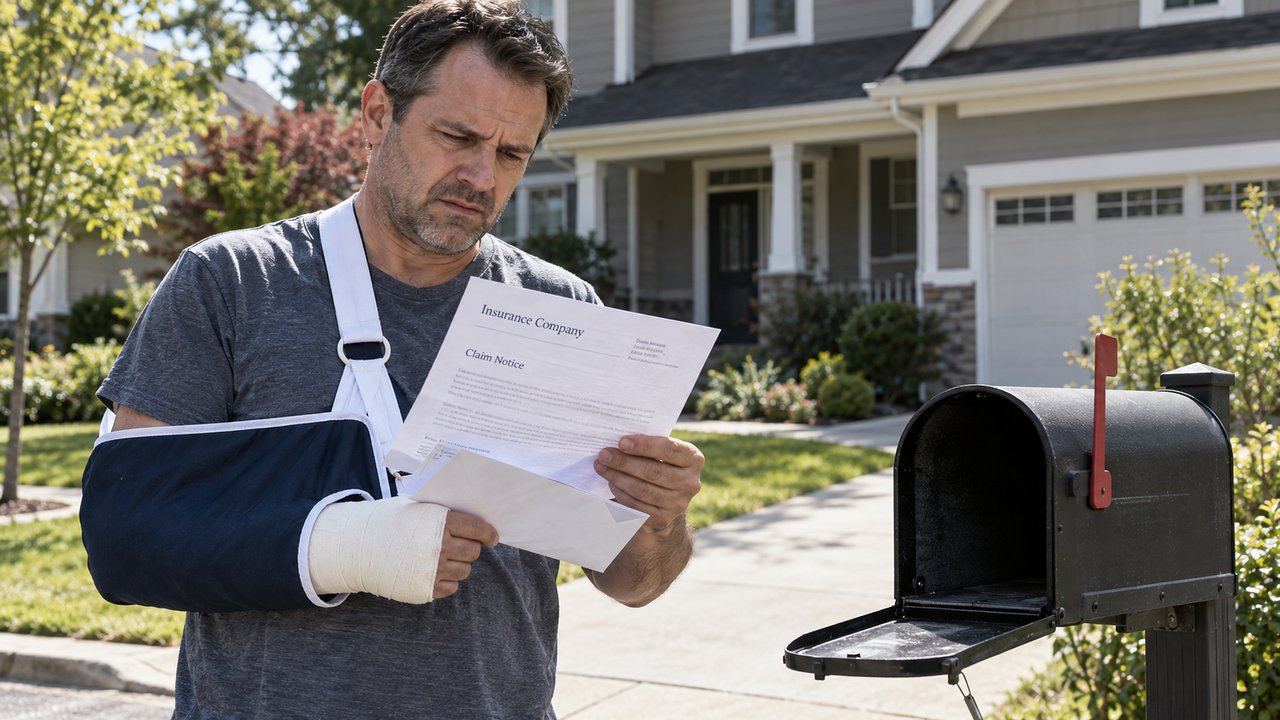
The injury case is behind you. Maybe it was a rear-end collision on the way home from a guys weekend, or a car that cut across your lane on a bike tour. The settlement is signed, and for the first time in months life feels close to normal. Then an envelope arrives from a company you barely recognize, asking for a chunk of that settlement.
The letter may come from your health insurer or from a recovery company working on its behalf. It references medical bills from the accident and asks to be reimbursed. For a lot of guys, it is the first time they have heard the word subrogation. These requests follow rules, and those rules can be checked before you write a check. Subrogation lets one party step into the shoes of another to recover money. In health insurance, it usually means a plan that paid for accident-related treatment seeks repayment when someone else turns out to be responsible for the injury. The idea is to prevent double recovery. If your health plan paid the medical bills and the at-fault driver's insurer later paid for those same expenses in a settlement, the plan may claim a right to be repaid from that money. Canada New England cruises feature walkable breweries in Halifax, Portland, and Boston. Late port departures let you explore Moosehead, Allagash, and Dieu du Ciel without rushing. Experience Croatia's Adriatic Sea through luxury yacht charters, cruise adventures, and island hopping. Discover Hvar's nightlife, Kornati's wilderness, and Mljet's pristine forests on the ultimate gu Curated Sri Lanka journeys from a passionate local team, ideal for travelers seeking culture, landscapes and lasting memories. A 12-day guided motorcycle tour through Northern Thailand's misty mountains and hill tribe villages, ideal for riders seeking adventure and comfort. Promoted by FlowAds Large insurers often hand these claims to recovery companies. Optum, for example, manages subrogation and recovery work for UnitedHealthcare plans. An Optum subrogation letter typically identifies the accident, lists the related medical payments, and asks how the injury claim was resolved. After an accident, medical care can't wait for a liability claim to be sorted out. Hospitals and doctors bill your health insurance right away, and the plan pays under its normal rules, often months before anyone settles anything. Liability claims move slowly. Investigating fault, finishing treatment, and negotiating a settlement can take a year or more, and during that stretch the plan may have paid thousands toward emergency care, surgery, physical therapy, and prescriptions. Why we picked it: a grill you can actually carry to the campsite, the tailgate or the cabin without borrowing a truck. Stainless, no propane tank to wrestle, and hot enough to cook for four guys rather than reheat for one. Promoted by FlowAds Many health plans include language reserving the right to be repaid if another party is responsible. The plan covered your care when you needed it, and the same plan documents set up the reimbursement request that shows up later. Plan terms come first. The policy or plan documents usually spell out reimbursement rights, including whether the plan expects repayment from the first dollar of a settlement or whether reductions apply for attorney fees. The type of plan matters just as much. Many employer plans are governed by the federal law known as ERISA, and self-funded ERISA plans can often enforce their terms even where state law would otherwise limit recovery. Fully insured plans are more likely to be bound by state rules. Those state rules vary. Texas, for example, has a statute that limits reimbursement for certain insured plans, including a reduction tied to the attorney fees that produced the settlement. Disputes also come up over which charges actually relate to the accident. A qualified attorney can help determine which rules apply to your plan before any money changes hands. Travel adds a few wrinkles. A crash in another state means that state's fault and insurance rules usually govern the injury claim, while your health plan's reimbursement rights still come from your plan documents back home. If you are piecing together what happened after a crash on the road, our road trip safety guide covers the reporting steps and claim deadlines that vary by state. Cyclists run into this often. When a driver hits a rider, auto coverage, health insurance, and the driver's liability policy can all end up paying pieces of the same hospital bill, and each one may want its share back. Our breakdown of what to do if you are injured on a bike tour walks through whose insurance pays first. A travel medical policy can also carry its own recovery clause, so read it with the same eye you give your health plan. If you are still sorting out what a trip policy does and doesn't cover, this comparison of travel insurance vs life insurance is a good starting point. Start by verifying the sender. Call the number on your insurance card, not the one printed in the letter, and confirm the company is acting for your plan. That one call helps you avoid scams and misdirected requests. Next, request an itemized list of charges and go through it line by line. Routine checkups, unrelated prescriptions, and treatment for preexisting conditions sometimes land on these lists and inflate the amount being claimed. Then ask for a copy of the plan documents that describe reimbursement rights. Confirm whether the plan is self-funded or insured, and compare the amount requested with what the plan actually paid. Plans usually negotiate discounts with providers, so the billed amount and the paid amount are rarely the same number. A settlement doesn't always close the books on an injury claim, and the first number on a reimbursement letter is rarely the final one. Once the charges are verified, there are two common reasons to ask for a reduction. The first is attorney fees. Your lawyer's work produced the settlement the plan is collecting from, so many plans, and some state laws, reduce the claim by a share of those fees and costs. The second is a settlement that didn't cover your full losses, which happens often when the at-fault driver carried low policy limits. Pointing that out, with the numbers, gives the plan a reason to take less than the full amount. Whatever you agree to, get it in writing before any money moves. When the amount is significant or the plan's rules are unclear, a qualified attorney can sort out what you actually owe and handle the negotiation for you. Promoted by FlowAdsWhat Do You Call Your "Guys Trips"?
What Is Subrogation And Why Does It Exist?
Best Breweries to Visit on a Canada and New England Cruise
Adriatic Cruising: Why Croatia's Islands Are Perfect for Your Next Mancation

Discover the Essence of Sri Lanka

North Thailand Motorcycle Tour to Conquer the Mountains of Mist

Why Your Health Plan Paid Bills It Now Wants Back
Man Gear Pick of the Month
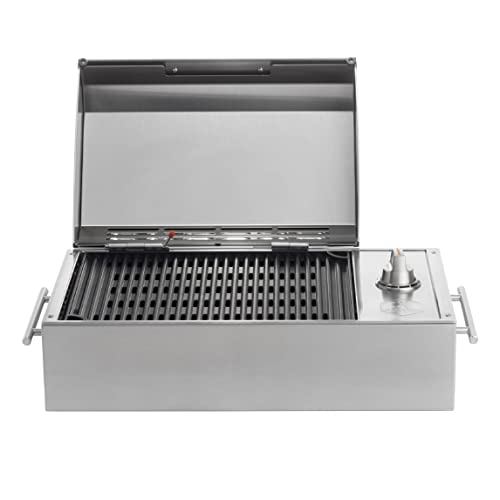
Kenyon City Grill Portable Stainless Steel Electric Grill
 August's Pick LiberNovo Maxis Electric Big and Tall Ergonomic Office Chair, Graphite 52cm $1,393.00
 July's Pick Powerful Propane Torch Gun, Adjustable Flame Thrower Gun, Kitchen Torch with Detachable Design, Flamethrower Blow Torch for BBQ, Searing Steak, Welding, Camping Charcoal Lighter(Tank Not Included) $42.99
 June's Pick OYASUMI Funny BBQ Man Hot Dog Holders, 4 PCS Reusable Stainless Steel Sausage Stands, Portable Hot Dog Roasters, Barbecue Grill Accessories for Camping & Party Gifts $7.98

How Insurers Decide What They Can Recover
When The Accident Happened On A Trip
What To Check Before You Respond To A Subrogation Demand
Paying Back A Health Plan Is Often Negotiable

